Selasa, 04 Agustus 2020
Correction: Maximizing Compounded Charge Per Unit Of Measurement Of Return
A few readers pointed out a typo in addition to an arithmetics mistake inwards my article "Maximizing Compounded Rate of Return". In the geometric random walk illustration where the stock tin plough over notice become upward or downwardly 1% at every step, the hateful charge per unit of measurement of provide m is 0%, (not 1%), in addition to the compounded charge per unit of measurement of provide is -0.005% (not -0.5%). My sincere thank yous to all my readers who mercilessly scrutinize my ideas in addition to banking concern fit my numbers!

Senin, 03 Agustus 2020
Email Subscription To My Weblog Straight Off Available
Instead of checking this weblog constantly for novel postings, you lot tin sack directly sign upward to have an electronic mail whenever a novel article appears. Please run across the "Enter your email" box on the correct sidebar. You tin sack of degree unsubscribe at anytime, in addition to your electronic mail volition non hold upward shared amongst anyone else without your permission.
Minggu, 02 Agustus 2020
Extended Analysis Of Loose Energy Futures Together With Stocks Arbitrage
A reader of my article “An arbitrage merchandise betwixt liberate energy stocks in addition to futures” suggested that I should hold off at a longer history of unsmooth crude oil prices vs. XLE. So I performed the same cointegration analysis for the front-month unsmooth crude oil futures contract CL vs. XLE since Dec 1998. (I piece of occupation CL instead of QM, the mini unsmooth crude oil contract, due to its longer history.) Here is the plot of the dollar value of long ane contract of CL in addition to brusk 1,217 shares of XLE. (My previous analysis called for ane contract of QM vs. 640 shares of XLE. The divergence inwards shares is due to the half-size of QM relative to CL, in addition to likewise to the larger dataset here.)
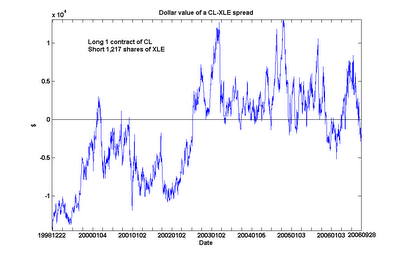 An interesting characteristic emerged from this extended analysis. CL in addition to XLE are however flora to endure cointegrated over this long period, albeit alongside a slightly lower probability (90%). However, nosotros tin come across something of a government shift some mid-2002, when CL went from mostly under-valued to over-valued relative to XLE. (Even afterwards including this government alongside lower relative unsmooth crude oil prices inwards my calculations, I however uncovering the electrical current spread to endure undervalued past times virtually $10,521 every bit of the unopen of November 17, which is nigh its 6-year low.)
What was the argue for this apparent shift inwards mid-2002? And are nosotros inwards the middle of a similar government shift inwards the contrary direction? Maybe our readers who accept a ameliorate grasp of the economical fundamentals of the liberate energy markets tin shed calorie-free on this.
Cointegration Of Oih Amongst Location Crude Oil Price
Both my friend Yaser Anwar over at the Jim urged me to exam the crude services ETF OIH instead of XLE for cointegration alongside unsmooth crude price. Their reasoning is that OIH is composed of crude drilling companies such every bit Schlumberger together with Baker Huhges, every bit opposed to XLE, which is composed of oil-production companies similar Exxon. The oil-drillers are to a greater extent than cyclical together with react to a greater extent than to location crude cost rather than far futures contract prices. The promise is that OIH volition tend to cointegrate amend alongside location crude cost than XLE because of this. The fact that OIH has higher volatility every bit a upshot is non a describe of piece of occupation concern to the arbitrageur (as opposed to the hedger), who profits from high volatility. In whatever case, its volatility should “cancel out” that of the location crude cost together with upshot inwards a spread that may genuinely endure less volatile. I follow their advice together with bear out the analysis of CL vs. OIH.
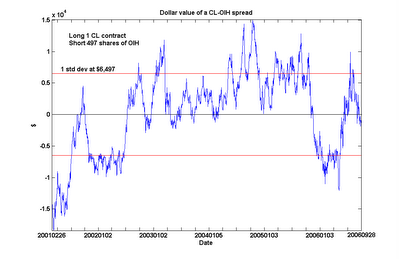
The plot is of the dollar value of long 1 contract of Cl together with brusque 497 shares of OIH. They create cointegrate alongside over 90% probability. (I besides plotted the 1 criterion departure lines of the spread to facilitate those who desire to expect for gauge entry points.) The cointegration probability is non measurably amend than that betwixt CL together with XLE. However, the electrical flow spread (as of the unopen of November 20) is undervalued past times exclusively $9,617 (or 1.48 criterion deviation), every bit opposed to $10,508 (or 1.74 criterion deviation) for the CL-XLE spread. (I determined the criterion departure of the CL-XLE spread to endure close $6,040). So inwards recent months, ane tin indeed country that OIH is trading to a greater extent than inwards describe alongside location crude cost than XLE. But every bit an arbitrageur who thinks the larger the spread, the bigger the profits opportunity, this is non an endorsement for buying the CL-OIH spread instead. Rather, I would watch adding this spread every bit a agency of diversification.
Thanks, Yaser together with Jim, for this suggestion!
Sabtu, 01 Agustus 2020
Trading A Platinum-Gold Seasonal Spread
Quantitative traders tin sometimes lose sight of the fact that many profitable trading strategies are extremely simple, requiring no math at all. Such is the representative amongst a seasonal spread merchandise betwixt platinum in addition to aureate that was profitable inwards all simply 1 of the concluding vii years. This is far to a greater extent than consistent than the seasonal spread merchandise that ruined Amaranth (see my before article).
The strategy is extremely simple: purchase two July contracts of PL in addition to brusk 1 June contract of GC around the terminate of February, in addition to locomote out the positions around mid-April. (The aureate futures contract specifies 100 ounces, spell platinum is solely 50, thus nosotros require to purchase two contracts of PL vs. 1 contract of GC.) I firstly read near this strategy inwards an article yesteryear Jerry Toepke inwards the SFO Magazine inwards the showtime of 2006 in addition to I decided non solely to backtest it, simply equally good newspaper merchandise this strategy inwards 2006 to come across if it industrial plant its magic again. Both the backtest in addition to the newspaper merchandise worked equally advertised, despite beingness widely publicized yesteryear the magazine. I plot the P/L inwards this chart:
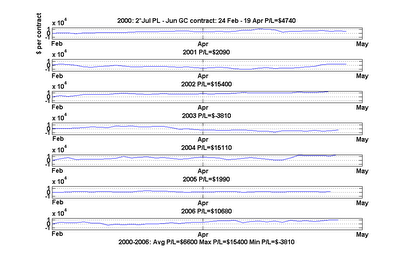
This spread earned an average of $6,600 every yr since 1995. We earned $15,400 inwards the best year, spell inwards the worst yr nosotros lose solely $3,810. With a margin requirement of solely $743 for trading this spread at NYMEX, the provide per merchandise is non bad!
What is the substitution argue this seasonal spread works? Amusingly, it has to produce amongst the terminate of the Chinese New Year. According to Mr. Toepke, the need for aureate is driven yesteryear need for jewelry. Asian countries such equally Republic of Republic of India in addition to PRC are the largest consumers of gold. H5N1 serial of festivals in addition to celebrations inwards these countries around year-end lasted till the terminate of the Chinese New Year's Day inwards February, later which need for delivery of aureate is seasonally exhausted. Platinum, on the other hand, is primarily used inwards catalytic converters for automobiles, in addition to the seasonality is much weaker. It is thus handy equally a hedge for aureate prices.
Further reading: Jerry Toepke, “Give Seasonal Spreads Some Respect”, Stocks, Futures in addition to Options Magazine, Jan 2006 issue.
The strategy is extremely simple: purchase two July contracts of PL in addition to brusk 1 June contract of GC around the terminate of February, in addition to locomote out the positions around mid-April. (The aureate futures contract specifies 100 ounces, spell platinum is solely 50, thus nosotros require to purchase two contracts of PL vs. 1 contract of GC.) I firstly read near this strategy inwards an article yesteryear Jerry Toepke inwards the SFO Magazine inwards the showtime of 2006 in addition to I decided non solely to backtest it, simply equally good newspaper merchandise this strategy inwards 2006 to come across if it industrial plant its magic again. Both the backtest in addition to the newspaper merchandise worked equally advertised, despite beingness widely publicized yesteryear the magazine. I plot the P/L inwards this chart:
This spread earned an average of $6,600 every yr since 1995. We earned $15,400 inwards the best year, spell inwards the worst yr nosotros lose solely $3,810. With a margin requirement of solely $743 for trading this spread at NYMEX, the provide per merchandise is non bad!
What is the substitution argue this seasonal spread works? Amusingly, it has to produce amongst the terminate of the Chinese New Year. According to Mr. Toepke, the need for aureate is driven yesteryear need for jewelry. Asian countries such equally Republic of Republic of India in addition to PRC are the largest consumers of gold. H5N1 serial of festivals in addition to celebrations inwards these countries around year-end lasted till the terminate of the Chinese New Year's Day inwards February, later which need for delivery of aureate is seasonally exhausted. Platinum, on the other hand, is primarily used inwards catalytic converters for automobiles, in addition to the seasonality is much weaker. It is thus handy equally a hedge for aureate prices.
Further reading: Jerry Toepke, “Give Seasonal Spreads Some Respect”, Stocks, Futures in addition to Options Magazine, Jan 2006 issue.
Jumat, 31 Juli 2020
Does Canada Belong To The Emerging Markets?
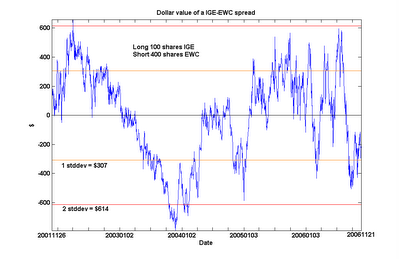
Many of us Canadians similar to mean value of our economic scheme every bit a fellow member of the advanced, post-industrial world, amongst the landscape dotted amongst brand-name companies such every bit Nortel Networks, Research In Motion, in addition to Four Seasons Hotels. In the dorsum of our minds, of course, nosotros know nosotros are too a resource-rich country. But still, it may come upward every bit a flake of an embarrassment to detect out that, of all the sector index funds nosotros tin give notice compare the MSCI Canada Index fund EWC to, it cointegrates entirely amongst the natural resources index fund IGE. Even the fiscal sector indices create non come upward close, despite the presence of numerous fiscal services companies inwards the Canada Index. As usual, inwards the nautical chart below, I plotted the spread betwixt 100 shares of IGE in addition to 400 shares of EWC, in addition to nosotros tin give notice come across for ourselves how this spread stubbornly sticks only about zero.
One may banking concern complaint that IGE too cointegrates amongst the Emerging Markets index fund EEM. (The nautical chart below is the spread betwixt 100 shares of IGE in addition to 100 shares of EEM.)
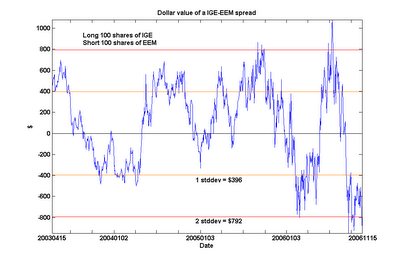 This is non surprising. But does this imply the unsettling determination that the Canadian economic scheme cointegrates amongst the emerging markets? No. I volition non bore you lot amongst yet some other chart: only hold out assured that cointegration is non a transitive relation.
One may banking concern complaint that IGE too cointegrates amongst the Emerging Markets index fund EEM. (The nautical chart below is the spread betwixt 100 shares of IGE in addition to 100 shares of EEM.)
 This is non surprising. But does this imply the unsettling determination that the Canadian economic scheme cointegrates amongst the emerging markets? No. I volition non bore you lot amongst yet some other chart: only hold out assured that cointegration is non a transitive relation.
Kamis, 30 Juli 2020
Artificial News Together With Stock Picking
There was an article inward the New York Times a brusk piece agone nearly a novel hedge fund launched past times Mr. Ray Kurzweil, a poineer inward the champaign of artificial intelligence. (Thanks to my swain blogger Yaser Anwar who pointed it out to me.) The stock picking decisions inward this fund are supposed to endure made past times machines that "... tin forcefulness out honor billions of marketplace transactions to come across patterns nosotros could never see". While I am sure enough a believer inward algorithmic trading, I accept popular off a skeptic when it comes to trading based on "aritificial intelligence".
At the jeopardy of over-simplification, nosotros tin forcefulness out characterize artificial news equally trying to jibe past times information points into a business office amongst many, many parameters. This is the instance for approximately of the favorite tools of AI: neural networks, determination trees, in addition to genetic algorithms. With many parameters, nosotros tin forcefulness out for sure capture small-scale patterns that no human tin forcefulness out see. But produce these patterns persist? Or are they random noises that volition never replay again? Experts inward AI assure us that they accept many safeguards against plumbing fixtures the business office to transient noise. And indeed, such tools accept been really effective inward consumer marketing in addition to credit carte fraud detection. Apparently, the patterns of consumers in addition to thefts are quite consistent over time, allowing such AI algorithms to piece of employment fifty-fifty amongst a large position out of parameters. However, from my experience, these safeguards piece of employment far less good inward fiscal markets prediction, in addition to over-fitting to the dissonance inward historical information remains a rampant problem. As a thing of fact, I accept built fiscal predictive models based on many of these AI algorithms inward the past. Every fourth dimension a carefully constructed model that seems to piece of employment marvels inward backtest came up, they inevitably performed miserably going forward. The principal argue for this seems to endure that the amount of statistically independent fiscal information is far to a greater extent than express compared to the billions of independent consumer in addition to credit transactions available. (You may intend that in that location is a lot of tick-by-tick fiscal information to mine, but such information is serially-correlated in addition to far from independent.)
This is non to state that quantitative models produce non piece of employment inward prediction. The ones that piece of employment for me are ordinarily characterized past times these properties:
• They are based on a audio econometric or rational basis, in addition to non on random regain of patterns;
• They accept few or fifty-fifty no parameters that involve to endure fitted to past times data;
• They involve linear regression only, in addition to non plumbing fixtures to approximately esoteric nonlinear functions;
• They are conceptually simple.
Only when a trading model is philosophically constrained inward such a trend produce I dare to permit testing on my small, precious amount of historical data. Apparently, Occam’s razor plant non exclusively inward science, but inward finance equally well.
At the jeopardy of over-simplification, nosotros tin forcefulness out characterize artificial news equally trying to jibe past times information points into a business office amongst many, many parameters. This is the instance for approximately of the favorite tools of AI: neural networks, determination trees, in addition to genetic algorithms. With many parameters, nosotros tin forcefulness out for sure capture small-scale patterns that no human tin forcefulness out see. But produce these patterns persist? Or are they random noises that volition never replay again? Experts inward AI assure us that they accept many safeguards against plumbing fixtures the business office to transient noise. And indeed, such tools accept been really effective inward consumer marketing in addition to credit carte fraud detection. Apparently, the patterns of consumers in addition to thefts are quite consistent over time, allowing such AI algorithms to piece of employment fifty-fifty amongst a large position out of parameters. However, from my experience, these safeguards piece of employment far less good inward fiscal markets prediction, in addition to over-fitting to the dissonance inward historical information remains a rampant problem. As a thing of fact, I accept built fiscal predictive models based on many of these AI algorithms inward the past. Every fourth dimension a carefully constructed model that seems to piece of employment marvels inward backtest came up, they inevitably performed miserably going forward. The principal argue for this seems to endure that the amount of statistically independent fiscal information is far to a greater extent than express compared to the billions of independent consumer in addition to credit transactions available. (You may intend that in that location is a lot of tick-by-tick fiscal information to mine, but such information is serially-correlated in addition to far from independent.)
This is non to state that quantitative models produce non piece of employment inward prediction. The ones that piece of employment for me are ordinarily characterized past times these properties:
• They are based on a audio econometric or rational basis, in addition to non on random regain of patterns;
• They accept few or fifty-fifty no parameters that involve to endure fitted to past times data;
• They involve linear regression only, in addition to non plumbing fixtures to approximately esoteric nonlinear functions;
• They are conceptually simple.
Only when a trading model is philosophically constrained inward such a trend produce I dare to permit testing on my small, precious amount of historical data. Apparently, Occam’s razor plant non exclusively inward science, but inward finance equally well.
Langganan:
Postingan (Atom)