I argued earlier inwards the outset of Oct ("An arbitrage merchandise betwixt issue energy stocks as well as futures") that issue energy stocks are overvalued relative to issue energy futures. At that time, a portfolio of long one forepart calendar month QM (crude oil Emini time to come contract) as well as curt 640 shares of XLE (energy stocks ETF) has a value of -$2,584. Where is it now? As of the closed of Oct 31, Dec QM is at $58.725, piece XLE is at $55.73 a share. The portfolio is straightaway at -$6,305 (the multiplier for QM is 500). The spread has clearly widened: it is straightaway at a 3-year low.
We are straightaway faced alongside the park arbitrage trader's quandary. Is this an unprecendented profits chance to double upwardly on this trade, or was this a colossal blunder on my part? I came across this New York Times article most the earnings reports from Exxon as well as Shell that gave me approximately comfort. While both issue energy companies posted huge profits, the article quoted Fadel Gheit, a senior issue energy analyst at Oppenheimer & Company, that for the 4th quarter, "“the enquiry is non if earnings volition decline, the enquiry is past times how much.” According to the article, analysts enjoin that for every dollar the toll of a barrel of unsmooth oil drops, Exxon forgoes $500 1000000 inwards profit.
So yes, alongside my fingers crossed, I am nevertheless waiting for the hateful solar daytime when this spread closes up.
Selasa, 11 Agustus 2020

Senin, 10 Agustus 2020
Gold Vs. Gold-Miners: Roughly Other Arbitrage Opportunity?
Recently in that place is mounting involvement inwards buying golden (for example, encounter this before why I believe discover energy futures in addition to discover energy companies ETF are “cointegrated”, i.e. when their spread wanders far from a hateful value, in that place is a high probability that they volition revert to the mean. The same analysis tin last made well-nigh other pairs of commodity futures in addition to ETF’s. Therefore I apply this to gold.
Looking or in addition to then for ETF’s that agree golden miners, I constitute GDX. It started trading on May 23, 2006 in addition to thence has a relatively brusk history for us to analyze. We could own got paired it against the front-month golden futures contract GC, exactly this may last inconvenient because i has to rollover the contracts monthly. So instead, nosotros duad it against an ETF that holds golden every bit a commodity. GLD is i such example. (So is IAU, exactly GLD is far to a greater extent than liquid.) Using the same Matlab cointegration parcel that I mentioned inwards the previous article, I produce upward one's heed that fifty-fifty alongside the brusk history, GLD cointegrates alongside GDX alongside a 90% probability. Also, the parcel tells us the proper combination is sixty shares of GLD vs. 100 shares of GDX. So if nosotros bird a duad yesteryear buying sixty shares of GLD in addition to shorting 100 shares of GDX, nosotros tin plot the value over fourth dimension here:
Looking or in addition to then for ETF’s that agree golden miners, I constitute GDX. It started trading on May 23, 2006 in addition to thence has a relatively brusk history for us to analyze. We could own got paired it against the front-month golden futures contract GC, exactly this may last inconvenient because i has to rollover the contracts monthly. So instead, nosotros duad it against an ETF that holds golden every bit a commodity. GLD is i such example. (So is IAU, exactly GLD is far to a greater extent than liquid.) Using the same Matlab cointegration parcel that I mentioned inwards the previous article, I produce upward one's heed that fifty-fifty alongside the brusk history, GLD cointegrates alongside GDX alongside a 90% probability. Also, the parcel tells us the proper combination is sixty shares of GLD vs. 100 shares of GDX. So if nosotros bird a duad yesteryear buying sixty shares of GLD in addition to shorting 100 shares of GDX, nosotros tin plot the value over fourth dimension here:
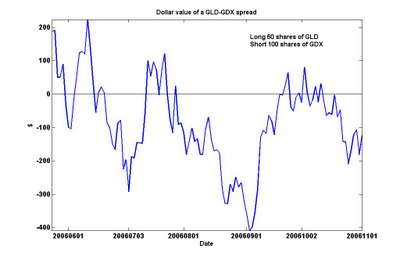
There are some caveats alongside trading this spread. First, it is non ever slowly to borrow GDX or GLD to short. It depends on if your broker has a expert securities lending desk. Secondly, the history of GDX is short. So whatsoever analysis must last taken alongside a grain of salt. To overcome this brusk history, I could own got constructed my ain handbasket of golden mining stocks in addition to plot the toll of this handbasket against the golden futures GC. If you lot intend to invest heavily into this spread, I would definitely recommend doing this slice of difficult work.
Minggu, 09 Agustus 2020
Cointegration Is Non The Same Every Minute Correlation
A reader asked me latterly why I believe that liberate energy stock prices (e.g. XLE) are correlated amongst unsmooth crude futures front-month contract (QM). Actually I don’t believe they are necessarily correlated – I solely recollect they are “cointegrated”.
What is the departure betwixt correlation as well as cointegration? If XLE as well as QM were actually correlated, when XLE goes upwards i day, QM would probable acquire upwards too on the same day, as well as vice versa. Their daily (or weekly, or monthly) returns would accept risen or fallen inwards synchrony. But that’s non what my analysis was about. I claim that XLE as well as QM are cointegrated, pregnant that the 2 toll serial cannot wander off inwards reverse directions for real long without coming dorsum to a hateful distance eventually. But it doesn’t hateful that on a daily terra firma the 2 prices accept to motion inwards synchrony at all.
Two hypothetical graphs illustrate the differences. In the outset graph, stock Influenza A virus subtype H5N1 as well as stock B are correlated. You tin encounter that their prices motion inwards the same management almost everyday.
 Now catch stock Influenza A virus subtype H5N1 as well as stock C.
 Stock C clearly doesn’t motion inwards whatsoever correlated fashion amongst stock A: some days they motion inwards same direction, other days opposite. Most days stock C doesn’t motion at all! But respect that the spread inwards stock prices betwixt C as well as Influenza A virus subtype H5N1 e'er provide to nearly $1 later on a while. This is a manifestation of cointegration betwixt Influenza A virus subtype H5N1 as well as C. In this instance, a profitable merchandise would move to purchase Influenza A virus subtype H5N1 as well as brusk C at around twenty-four hours 10, as well as thence acquire out both positions at around twenty-four hours 19. Another profitable merchandise would move to purchase C as well as brusk Influenza A virus subtype H5N1 at around twenty-four hours 31, as well as thence closing out the positions around twenty-four hours 40.
Cointegration is the foundation upon which distich trading (“statistical arbitrage”) is built. If 2 stocks only motion inwards a correlated manner, in that place may never move whatsoever widening of the spread. Without a temporary widening of the spread inwards either direction, in that place is no chance to brusk (or buy) the spread, as well as no argue to await the spread to revert to the hateful either.
For farther reading:
Alexander, Carol (2001). Market Models: Influenza A virus subtype H5N1 Guide to Financial Data Analysis. John Wiley & Sons.
Sabtu, 08 Agustus 2020
Are Political Futures Markets Actually Predictive?
Today I volition accept a brief pause from quantitative trading inward the fiscal markets. Instead, I volition accept a critical await at political futures markets. There has been a lot of enthusiasm lately for such markets (e.g. www.tradesports.com, based inward Ireland, is the most pop one.) Media pundits together with scholars alike produce got oft said that these markets offering a ameliorate prediction of election outcomes than thought polls, sometimes claiming that they trounce polls three-quarters of the time. I produce got been an avid player inward these markets, simply I would similar to offering a contrarian view: I believe that these markets oft follow, rather than predict, events. The so-called “predictability” of these markets is oft ill-defined. The prediction changes constantly over time, together with and so depending on when you lot accept a snapshot of the markets, you lot tin e'er detect an 2nd when, retrospectively, the prediction matches the actual election outcomes really closely.
As an example, I watched alongside entertainment the tradesports.com futures marketplace prediction of the Virginia Senate race betwixt Democrat Jim Webb together with Republican George Allen. This is ane of the 2 unopen races that volition decide the command of the Senate. For months, the marketplace predicts that the Democrat volition lose (the probability of winning, which is the same equally the cost divided yesteryear 100, is e'er below 50% until the laid about of November). Then inward November, the marketplace began to run into the light, together with started to predict a Democratic win. See the nautical chart below.

But await what happened on the black of the election:

As the vote counts started to live on released, the marketplace initiative of all idea the Republican was going to win, driving the prices downwards to the teens. That was due to the votes from the conservative southern Virginia, which were the initiative of all to come upwards in. Then, equally the vote counts from the to a greater extent than liberal northern Virginia were published at to a greater extent than or less 11:30 pm, the prices shot upwards to higher upwards $60, together with continued on to over $80. Clearly, the marketplace does non know to a greater extent than well-nigh the futurity than your average word anchor.
As soul interested inward the predictability of election outcomes based on futures markets, this raises a serious question. What is the proper fourth dimension to accept a snapshot of the market? Should it live on 1 calendar month earlier the election (in which instance this marketplace prediction failed, presuming a Democratic win later the recount)? Or should it live on 1 calendar week earlier the election, inward which instance this marketplace prediction succeeded? And without an respond to this question, how tin ane claim whether the prediction is accurate or inaccurate?
As an example, I watched alongside entertainment the tradesports.com futures marketplace prediction of the Virginia Senate race betwixt Democrat Jim Webb together with Republican George Allen. This is ane of the 2 unopen races that volition decide the command of the Senate. For months, the marketplace predicts that the Democrat volition lose (the probability of winning, which is the same equally the cost divided yesteryear 100, is e'er below 50% until the laid about of November). Then inward November, the marketplace began to run into the light, together with started to predict a Democratic win. See the nautical chart below.

But await what happened on the black of the election:

As the vote counts started to live on released, the marketplace initiative of all idea the Republican was going to win, driving the prices downwards to the teens. That was due to the votes from the conservative southern Virginia, which were the initiative of all to come upwards in. Then, equally the vote counts from the to a greater extent than liberal northern Virginia were published at to a greater extent than or less 11:30 pm, the prices shot upwards to higher upwards $60, together with continued on to over $80. Clearly, the marketplace does non know to a greater extent than well-nigh the futurity than your average word anchor.
As soul interested inward the predictability of election outcomes based on futures markets, this raises a serious question. What is the proper fourth dimension to accept a snapshot of the market? Should it live on 1 calendar month earlier the election (in which instance this marketplace prediction failed, presuming a Democratic win later the recount)? Or should it live on 1 calendar week earlier the election, inward which instance this marketplace prediction succeeded? And without an respond to this question, how tin ane claim whether the prediction is accurate or inaccurate?
Jumat, 07 Agustus 2020
A Commodities Fund Manager's Comments On Aureate Vs Gold-Miners Arbitrage
John Netto, a main inwards a commodities fund that focuses heavily on gold, wrote me the next concerning my article on arbitrage betwixt aureate too gold-miners: "... at that topographic point is a paradox that exists inwards many instances amongst aureate companies too the underlying metal, which could potentially unwind most pairs traders. This is the dynamic of non-recourse loans that companies accept on when doing a project. This would never present upwards inwards a quantitative model simply tin set companies inwards a orbit that when aureate rises, they tin acquire wound to approximately degree. Banks that create non-recourse loans demand the companies to sell futures to guarantee payment for the projection inwards example the toll of aureate falls. This way, they volition non lose if the projection no longer becomes a feasible trouble concern endeavour. If aureate rises, these companies must present massive mark-to-market losses on their books based on novel accounting rules. So the theory that aureate companies tin merchandise correlated to the toll of the underlying is correct, even then a dynamic exists that has the potential on a per fellowship footing to materially touching on that."
I notice Mr. Netto's comments really insightful. I would brand i farther point: if the mark-to-market accounting losses are temporary too volition recover adjacent quarter, nosotros tin hold off their stock prices to revert. This is precisely the cointegration scenario that I talked virtually -- a toll reversion afterward approximately catamenia of time, simply non a day-to-day or week-to-week correlation.
An Updated Analysis Of The Arbitrage Betwixt Golden Together With Gold-Miners
In my article nearly the arbitrage chance betwixt golden together with gold-miners, I cautioned that nosotros should direct keep the analysis amongst a grain of common salt because of the brusque history of GDX (a gold-miners ETF). Adam Phillips of Van Eck Global, the occupation solid which created GDX, has kindly pointed out to me that GDX is designed to rail the Amex Gold Miners Index, GDM, which has a much longer history. Hence I repeated the analysis amongst golden location prices vs. GDM for the final three years. The results confirm my before analysis amongst much higher statistical significance: GDM cointegrates amongst golden prices amongst over 99% probability. Here I plot the departure betwixt the location prices of 6.1 troy ounce of golden together with the GDM index multiplied yesteryear 3.68 (to compare amongst my before plot, I normalize the golden prices together with the GDM index together with then that the Gold-GDM spread yields around the same dollar value equally the GLD-GDX spread at whatever time):


The mean-reversion of this spread is fifty-fifty to a greater extent than obvious than my plot inwards the before article. Also, amongst the longer history, nosotros acquire a much improve experience for the gain of fluctuations. While the value of the spread is nearly -$213 equally of the unopen of November 9, it tin give the axe for certain acquire much lower before reverting, based on the highs together with lows of the final three years.
FOOTNOTE
A reader of my before article made an interesting comment nearly shorting ETF’s such equally GDX together with GLD. He argued that since ETF shares tin give the axe hold upwards constantly created, it should non require existing shares to hold upwards borrowed for shorting. I asked Mr. Phillips of Van Eck Global nearly this, together with he confirmed to me that a newer ETF similar GDX tin give the axe inwards fact hold upwards difficult to borrow. He went on to nation that the borrowing of ETF’s has nix to practice amongst the issuer. The issuer tin give the axe indeed practice an unlimited furnish of the shares, precisely the trader however demand to borrow them from his or her broker for shorting. He besides told me he is currently working difficult to eliminate whatever borrowing problems inwards GDX that may direct keep existed.
Kamis, 06 Agustus 2020
Gld-Gdx Spread Reverted To 0 This Morning
Just a quick banknote on the GLD-GDX spread that I accept been talking about. This morn (Nov 17) the negative spread completely reverted as well as has gone into positive territory.
Langganan:
Postingan (Atom)