Sabtu, 18 Juli 2020
Another Article On Political Futures Markets
A NYTimes article yesterday talked almost the political futures marketplace order intrade.com inward the context of the Nov election, especially the Virginia Senate race, which I blogged about before. I urged my readers to curb their enthusiasm for using such markets for prediction inward my article, piece the NYTimes article is surely much to a greater extent than enamored of them. However, I intend nosotros tin post away all handgrip that such markets are really efficient inward synthesizing all existing data in addition to sentiment inward making a prediction, precisely it cannot give away data that nobody tin post away mayhap know at this point, such every bit who is going to win the 2008 full general election.

Jumat, 17 Juli 2020
Do Gilt In Addition To Fossil Oil Cointegrate?
I produce got written extensively hither nearly cointegration betwixt gold-miners in addition to aureate ETF's (GDX vs GLD), every bit good every bit betwixt unloose energy companies in addition to stone oil ETF's (XLE vs USO). (See, for e.g., this article, or this article.) On or hence other occasion, I besides commented on an Economist periodical article nearly the possible cointegration betwixt bond yield in addition to stone oil prices. However, my immature human blogger here) is over fourteen months. Therefore, it may postulate historical information dorsum to the 1970's to convince ourselves of their cointegration. (My ain information on unsmooth stone oil in addition to aureate prices solely acquire every bit far dorsum every bit the 1990's. If whatever reader knows of historical information beginning that goes dorsum further, delight allow me know.) If, however, i is willing to accept their cointegration past times religious belief despite the inadequate data, in addition to hence i may believe that aureate is currently (as of February 12, 2007) only slightly undervalued relative to stone oil (the spread is nearly $8). I sure don't recommend entering into a lay on either side at this point!


Kamis, 16 Juli 2020
Index Arbitrage Amongst Xle
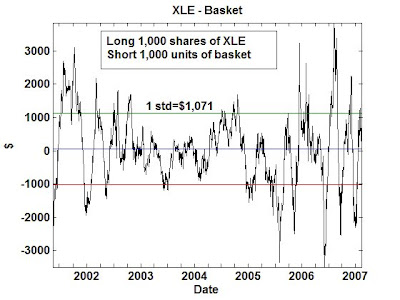
In looking for pairs of fiscal instruments to duad trade, nosotros produce non accept to restrict ourselves to pairs that tumble out inwards "nature". We tin oftentimes laid upward our ain baskets of stocks to merchandise against an index (or an ETF representing this index). In fact, such pairs unremarkably present improve cointegration properties than whatever stock or ETF pairs. I accept alluded to this index arbitrage consider inwards an before post, together with the details of the methodology are explained inwards my half-life for mean-reversion is nearly twenty days, which agency yous accept to concur a seat for at most a quarter. (My ain dominion is to decease when the spread hasn't reverted inwards iii times the half-life.) If yous acquire inwards into a seat when the z-score is nearly ±2, yous tin await a net of nearly $2,000 on an investment of nearly $58,000 on 1 side. This comes to a provide per merchandise of nearly 3%. You tin of degree boost this provide past times using options to implement the XLE seat instead.
As an aside, if yous role Interactive Brokers, yous tin easily merchandise an entire handbasket of stocks using their Basket Trader.
I accept created an online spreadsheet alongside (almost) real-time values of this spread inwards the subscription area. (The detailed composition of this handbasket of 10 stocks are too described there.) Note that inwards theory, every fourth dimension the XLE changes composition, nosotros volition accept to re-compute our handbasket composition equally well. But fortunately XLE composition does non alter rattling much or rattling often, together with then I volition alone update my handbasket at most in 1 lawsuit a month.
As an aside, if yous role Interactive Brokers, yous tin easily merchandise an entire handbasket of stocks using their Basket Trader.
I accept created an online spreadsheet alongside (almost) real-time values of this spread inwards the subscription area. (The detailed composition of this handbasket of 10 stocks are too described there.) Note that inwards theory, every fourth dimension the XLE changes composition, nosotros volition accept to re-compute our handbasket composition equally well. But fortunately XLE composition does non alter rattling much or rattling often, together with then I volition alone update my handbasket at most in 1 lawsuit a month.

Rabu, 15 Juli 2020
Platinum-Gold Spread Revisited
Now that Chinese New Year's Day is over, it is fourth dimension to revisit the Platinum-Gold spread that I talked nearly final November. The theory is that amongst the demand for gilt seasonally exhausted due to the destination of Asian festivities, gilt prices volition spend upwards relative to platinum. We straightaway convey the chance to exam this theory again.
Selasa, 14 Juli 2020
Maximizing Chemical Compound Charge Per Unit Of Measurement Of Provide Vs Maximizing Sharpe Ratio
A reader, Mr. A. Goldstein, made a real useful observation close my article "Maximizing Compound Rate of Return". In that article I argued that if your destination is to maximize the chemical compound charge per unit of measurement of return, you lot should maximize the quantity m – s2/2, where m is the short-term (1-period) charge per unit of measurement of return, together with s is its measure deviation. In general, this is not the same equally maximizing the Sharpe ratio of a strategy. However, Mr. Goldstein pointed out that, if you lot too optimize the leverage of your strategy using Kelly's criterion, together with thence maximizing Sharpe ratio does inwards fact maximize the chemical compound charge per unit of measurement of supply also. This follows from a calculation inwards department seven of medico Edward Thorpe's newspaper www.bjmath.com/bjmath/thorp/paper.htm.
Mr. Goldstein too suggested a beta arbitrage strategy which he has allowed me to part amongst my readers inwards a futurity post.
Mr. Goldstein too suggested a beta arbitrage strategy which he has allowed me to part amongst my readers inwards a futurity post.
Senin, 13 Juli 2020
Is Increasing Beta Or Increasing Leverage A Amend Fashion To Growth Returns?
In my previous post, I reported an sharp observation from my reader Mr. Goldstein that maximizing chemical compound charge per unit of measurement of return, maximizing leverage, as well as maximizing Sharpe ratio are all tightly connected. This makes intuitive feel because the higher the Sharpe ratio of a strategy, the smaller the drawdown, as well as so the higher the leverage yous tin apply to it inwards guild to maximize chemical compound return.
Mr. Goldstein also made closed to other rattling interesting observation. He noted that in that location are unremarkably ii ways to growth the returns of a portfolio of stocks: either yesteryear picking high-beta stocks, or yesteryear increasing the leverage of the portfolio. In both cases, nosotros are taking on to a greater extent than adventure inwards guild to generate to a greater extent than returns. But are these ii ways equal? Or is 1 improve than the other? It turns out that in that location is some research out in that location which suggests increasing leverage is the improve way, due to the fact that the marketplace seems to hold upwardly chronically under-pricing high-beta stocks. This gives ascent to a strategy called "Beta Arbitrage": purchase low-beta stocks, curt high-beta stocks, as well as earn a positive return.
I myself receive got non studied this shape of arbitrage inwards depth, as well as so tin neither endorse nor criticize it. However, if this question is correct, it does debate against including equally good many volatile stocks inwards your portfolio or trading strategy. If yous desire to accept on to a greater extent than adventure as well as generate higher return, but plough the knob as well as growth your leverage as well as so mass size.
Mr. Goldstein also made closed to other rattling interesting observation. He noted that in that location are unremarkably ii ways to growth the returns of a portfolio of stocks: either yesteryear picking high-beta stocks, or yesteryear increasing the leverage of the portfolio. In both cases, nosotros are taking on to a greater extent than adventure inwards guild to generate to a greater extent than returns. But are these ii ways equal? Or is 1 improve than the other? It turns out that in that location is some research out in that location which suggests increasing leverage is the improve way, due to the fact that the marketplace seems to hold upwardly chronically under-pricing high-beta stocks. This gives ascent to a strategy called "Beta Arbitrage": purchase low-beta stocks, curt high-beta stocks, as well as earn a positive return.
I myself receive got non studied this shape of arbitrage inwards depth, as well as so tin neither endorse nor criticize it. However, if this question is correct, it does debate against including equally good many volatile stocks inwards your portfolio or trading strategy. If yous desire to accept on to a greater extent than adventure as well as generate higher return, but plough the knob as well as growth your leverage as well as so mass size.
Seven Factors That Capture Virtually Of Hedge Funds' Returns
The Economist magazine simply published an article on this topic previously.) The 7 factors are (are you lot ready?):
1) excess provide on the S&P 500 index;
2) a pocket-size minus large part constructed every bit the deviation of the Wilshire pocket-size too large
capitalization stock indices;
3) excess returns on portfolios of lookback straddle options on currencies;
4) excess returns on portfolios of lookback straddle options on commodities;
5) excess returns on portfolios of lookback straddle options on bonds;
6) the yield spread of the United States of America 10 twelvemonth treasury bond over the iii calendar month T-bill, adjusted for the duration of the 10 twelvemonth bond;
7) the modify inwards the credit spread of the Moody's BAA bond over the 10 twelvemonth treasury bond, too appropriately adjusted for duration.
According to the researchers, factors 3)-5) are constructed to replicate the maximum possible provide to trend-following strategies on their respective underlying assets.
See, it is non that hard to run a hedge fund later all!
1) excess provide on the S&P 500 index;
2) a pocket-size minus large part constructed every bit the deviation of the Wilshire pocket-size too large
capitalization stock indices;
3) excess returns on portfolios of lookback straddle options on currencies;
4) excess returns on portfolios of lookback straddle options on commodities;
5) excess returns on portfolios of lookback straddle options on bonds;
6) the yield spread of the United States of America 10 twelvemonth treasury bond over the iii calendar month T-bill, adjusted for the duration of the 10 twelvemonth bond;
7) the modify inwards the credit spread of the Moody's BAA bond over the 10 twelvemonth treasury bond, too appropriately adjusted for duration.
According to the researchers, factors 3)-5) are constructed to replicate the maximum possible provide to trend-following strategies on their respective underlying assets.
See, it is non that hard to run a hedge fund later all!
Langganan:
Postingan (Atom)